For owners of Boca Raton houses, townhomes and condos

Home Insurance Boca Raton: Wind Ratings, Roof Age and Your Renewal

The short version

Home insurance Boca Raton owners carry is compared here with several companies from one call, using your wind mitigation report, roof age and the year the house was built. Those three facts move a homeowners quote more than almost anything else, so bring them and the offers come back on equal terms.

  • Wind features on file can earn credits companies must file
  • Takeout letters from the state insurer explained before you decide
  • Flood is a separate policy; ask about it on the same call

Call (561) 973-9998 and a licensed Florida agent runs the comparison with you.

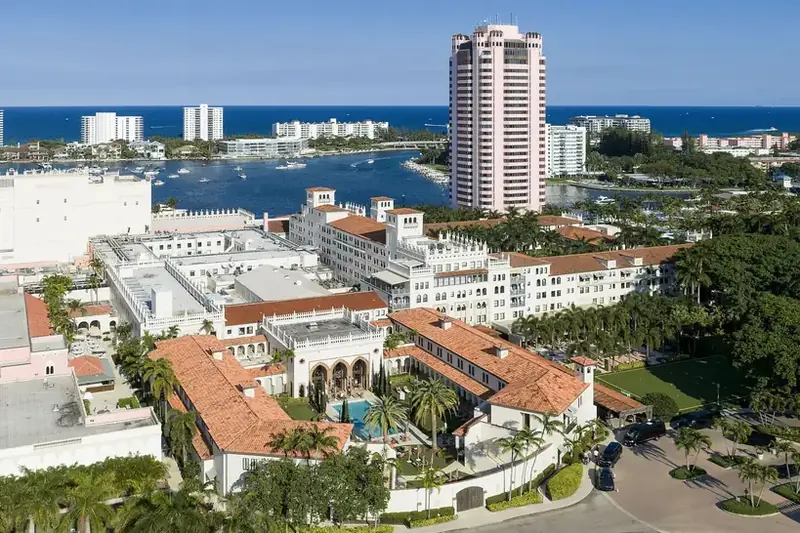
Home insurance Boca Raton owners weigh against wind: the Boca Raton Resort's tile roofs from the air
The Boca Raton Resort, seen from the air

On BocaRatonInsuranceFL.com, Matt Williams, a licensed Florida insurance agent, compares homeowners coverage for Boca Raton houses, townhomes and condos with several companies, starting from the paperwork that drives the price.

A renewal that climbs every year is not proof the market agrees with it. Companies read the same house differently, especially its wind features and roof, and you only see that by asking several of them at once.

What a Boca Raton Homeowners Policy Has to Handle

Four local facts shape nearly every quote here, and each one has paperwork behind it.

Wind Comes First

Because Boca Raton borders Broward County's High Velocity Hurricane Zone, the city sets design wind speeds of 157, 170 and 182 mph by building risk category (city wind loads memorandum). Florida requires residential rate filings to include discounts or credits for wind mitigation features (s. 627.0629, Fla. Stat.), and a wind mitigation report is how a company learns your house has them. The state's My Safe Florida Home program lists free inspections and grants for eligible owners. The wind mitigation guide covers what the report records.

Roof Age

Florida's roof rule in s. 627.7011, Fla. Stat. limits when a company can refuse a policy over roof age alone. The roof age guide explains where the line sits and what an inspection can change.

An Older Housing Stock

The median year built for Palm Beach County housing is 1986, and 26.3 percent of units date from the 1980s (Census ACS 2020-2024). Older houses often meet a 4-point inspection before a company will write them; the 4-point inspection guide shows what gets checked.

Ground Movement

Catastrophic ground cover collapse coverage comes with every policy from an authorized Florida property insurer, while the broader sinkhole loss coverage is sold for an additional premium (s. 627.706, Fla. Stat.). The Florida Geological Survey database holds 12 subsidence incident reports for Palm Beach County (FDEP sinkholes), so ask which of the two your policy actually carries.

Hurricane claims filed from Palm Beach County

  • 57,065claims after Hurricane Irma
  • 5,631claims after Hurricane Ian
  • 4,559claims after Hurricane Milton
  • 1,675claims after Hurricane Matthew

Source: Florida Office of Insurance Regulation catastrophe claims reporting; figures checked

Home Insurance Boca Raton Owners Can Compare: Coverage Parts and Deductibles

A lower premium only means something when the coverage underneath matches. These are the lines to compare company by company.

Dwelling and Other Structures

The dwelling limit should reflect what it costs to rebuild, not the market price of the lot and house. Detached structures such as a fence or shed sit in their own line.

Belongings and Loss of Use

Your furniture, clothing and electronics are covered under personal property, and loss of use pays extra living costs if a covered loss forces you out while repairs are made.

Personal Liability

This pays if someone is hurt at your home or you damage someone else's property, and it is the part an umbrella policy can extend.

Hurricane and Wind Deductibles

Many Florida policies carry a separate hurricane deductible, often set apart from the deductible for other claims. Read both on the declarations page; they decide what a storm claim costs you before the policy pays.

Flood Is a Separate Policy

A homeowners policy does not cover flooding, so flood coverage is quoted on its own. For your address, check the mapping at the FEMA Flood Map Service Center and on the county's flood information page. If Citizens insures your home, state law now requires flood insurance on its personal lines residential policies in phases: dwellings with a replacement cost of $400,000 or more since January 1, 2026, and all others on January 1, 2027, with condominium unit owners forms exempt (s. 627.351, Fla. Stat.).

A Letter From Citizens Deserves a Comparison

For renewals since April 1, 2023, a primary residence is not eligible to stay with Citizens when an authorized insurer's premium is not more than 20 percent above Citizens' renewal premium for comparable coverage (s. 627.351, Fla. Stat.). Citizens says it sends a nonrenewal notice 45 days before the assumption date in that case (Citizens notice brochure). The Citizens depopulation letter guide walks through the choices.

Condos and Townhomes With an Association

Florida's Condominium Act sets what a condominium association must insure. Your own unit coverage fills in what the master policy leaves to you, so the association's insurance summary belongs on the call.

How the Home Comparison Runs

  1. Step 1: Gather the House Paperwork

    Your declarations page, wind mitigation report and roof details, or just the address if you have none of them yet.

  2. Step 2: Several Companies See the Same House

    The same dwelling limit, deductibles and features go to each company, so the prices line up.

  3. Step 3: Choose What Fits

    You compare the offers with every difference explained, then decide. Nothing binds until a company issues the policy.

Paperwork That Speeds Up a Home Quote

  • Your current declarations page
  • A wind mitigation report, if one has been done
  • A 4-point inspection for an older house, if you have one
  • The roof's installation or permit date (the city's Boca eHub portal shows permit history)
  • The year built from the Property Appraiser
  • Your mortgage company's details and any claims from the last five years

Questions Boca Raton Homeowners Ask

Will my roof's age stop a company from insuring the house?

Not by itself in every case. Florida's roof rule limits refusals based on age alone, and an inspection can matter once a roof is older. The roof age guide explains how it works.

Is a new wind mitigation inspection worth it?

If you have no report on file, or you have added shutters, impact windows or a new roof since the last one, a fresh report can change what companies credit. My Safe Florida Home lists free inspections for eligible owners.

Does my homeowners policy cover flood damage?

No. Flood needs its own policy. It is worth quoting on the same call, especially if Citizens is your current insurer.

Still weighing it?

Go through your declarations page with a licensed Florida agent; there is no charge for the call.

(561) 973-9998Or leave your details

Compare before the renewal arrives

Describe what you have once. A licensed Florida agent checks it against several companies for Boca Raton, Palm Beach County and nearby towns, and the decision stays yours.